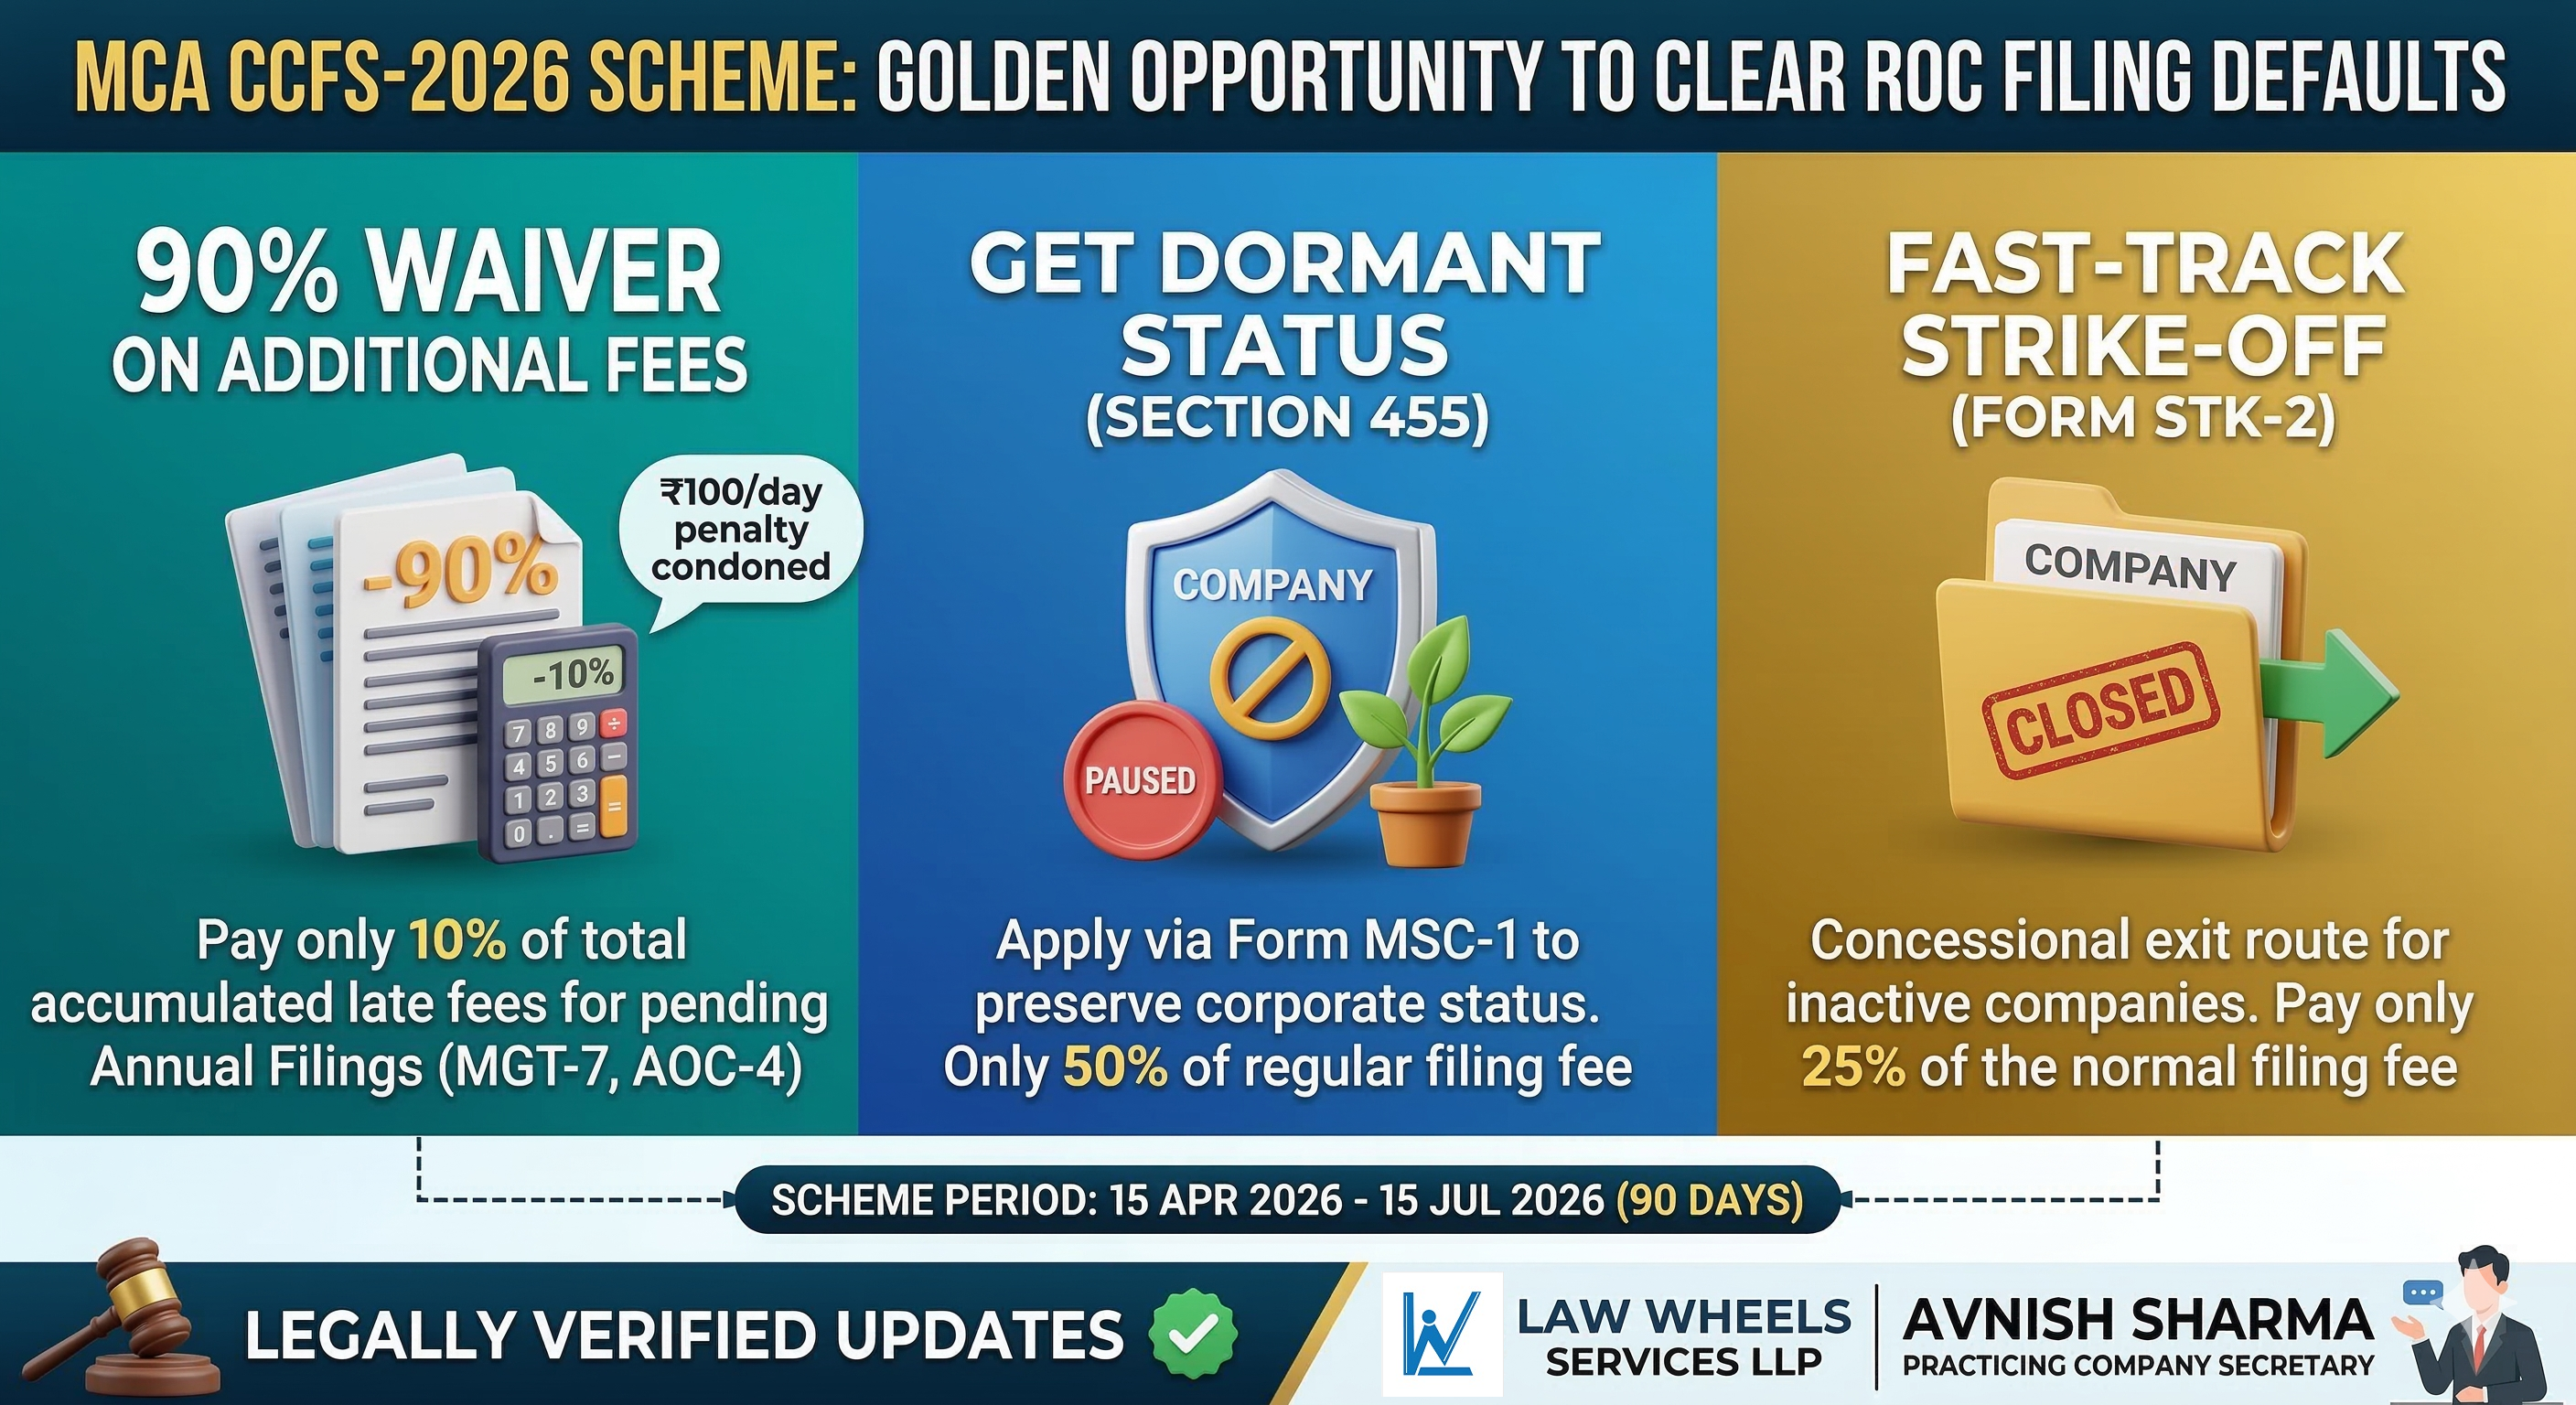
MCA CCFS-2026: Huge Relief for Pending ROC Filings & How to Save Penalties
The Ministry of Corporate Affairs (MCA) has dropped a massive compliance lifeline for Indian companies. If your company is struggling with pending annual returns, heavy late filing fees, or you want to close an inactive company, the wait is over.
On 24th February 2026, the MCA issued General Circular No. 01/2026, officially introducing the Companies Compliance Facilitation Scheme, 2026 (CCFS-2026). This temporary 90-day window is a golden opportunity to wipe the slate clean.
#What is the CCFS-2026 Scheme?#
The CCFS-2026 (Company Compliance Fresh Start Scheme) is a one-time condonation of delay initiative. It allows companies that have defaulted in filing their Annual Returns (Section 92) and Financial Statements (Section 137) to complete their filings at a drastically reduced cost and get immunity from prosecution.
Important Dates to Remember: The scheme window opens on April 15, 2026, and closes on July 15, 2026.
#Top 3 Benefits of CCFS-2026 for Companies#
This scheme isn't just about filing forms; it’s about strategic financial relief. Here is exactly how your company benefits:
| #Compliance Action# | #Regular Penalty / Cost# | #Relief Under CCFS-2026# |
|---|---|---|
| Pending Annual Filings | Normal Fee + ₹100 per day penalty (No upper limit) | Normal Fee + Only 10% of the total accumulated penalty. |
| Apply for Dormant Status | Full application fee | 50% Discount on normal filing fee for e-Form MSC-1. |
| Company Strike-Off | Full regular filing fee | Substantial discount (Pay only 25% of the fee). |
#Immunity from Prosecution: The Hidden Gem#
One of the most critical aspects of the CCFS-2026 scheme is immunity. If a company completes its pending filings under this scheme before the Adjudicating Officer issues a notice (or within 30 days of such notice), no further penalty or prosecution will be initiated regarding those specific delays.
However, directors should act fast. If the 30-day notice period expires without action, full penalties and the risk of director disqualification will apply.